A second set of rental rules in Ontario are set to take effect Sept. 21. Here is a link to Ontario Tribunals Page with information on the changes. The same information is presented here by the

Dated: March 13 2025
Views: 3
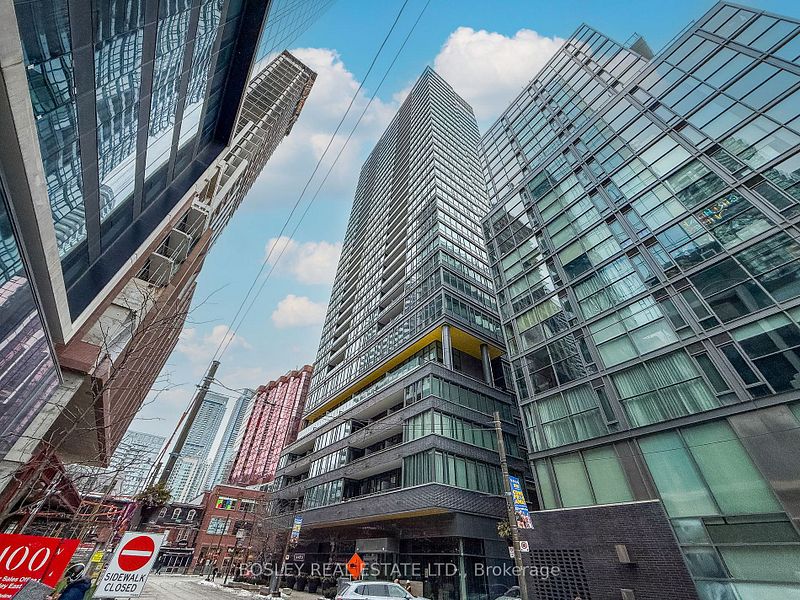
When purchasing a home, Toronto buyers have several options in terms of ownership structures, including condominiums, co-operatives (co-ops), and co-ownerships. Each of these comes with its own unique features, benefits, and considerations. Here’s a breakdown of the key differences to help you make an informed decision.
With a condominium, buyers acquire exclusive ownership of a specific unit. For most condominiums, this also includes a shared ownership stake in the common areas of the building (such as hallways, parking lots, and recreational facilities) as a tenant-in-common with other unit owners. However, in certain developments, parking spaces may be assigned individually, or owners may purchase parking "units" that can be sold separately from the residential unit.
Unlike co-operatives or co-ownerships, condominium buyers generally do not need approval from a Board of Directors to purchase a unit. The buying process is similar to purchasing a freehold home (such as a detached house), and financing is easily accessible with traditional mortgage options. Lenders can secure the mortgage directly against the unit title, making it straightforward to finance.
Condominium owners have the flexibility to lease their units. They can also reclaim possession of the unit for personal use with a 60-day notice before the lease ends, provided they wish to move in themselves.
Condo properties are typically managed by a Board of Directors elected by the owners. This Board hires a property management company to handle day-to-day operations, including maintenance, repairs, and managing finances. Before buying, it’s crucial for buyers to request an Estoppel Certificate to check the unit’s maintenance charges, whether there are any special assessments, and if there are any ongoing litigations.
When considering a condo, it’s also wise to inspect the common areas to assess the general upkeep and the likelihood of future repairs (e.g., checking for leaks in the underground parking garage).
In a co-operative, buyers don’t own their unit outright; instead, they purchase shares in a co-operative corporation that owns the building. Along with these shares, buyers receive an exclusive right to occupy a specific unit within the building. Since buyers don’t technically own the unit, securing financing can be more challenging. However, there are some lenders willing to offer financing by securing the buyer’s share interest in the co-op, but the loan limits tend to be lower compared to conventional mortgages, requiring a higher down payment.
Co-op units can also involve a blanket mortgage, which is a mortgage registered against the entire co-op building. If this applies, the buyer will share the responsibility for repaying the mortgage through their monthly fees. Buyers should ask about the potential impact of any unpaid mortgage obligations from other shareholders.
Another important distinction is that co-op buyers must receive approval from the co-op’s Board of Directors before purchasing. Typically, the purchase agreement will be conditional upon Board approval, which can take 10-14 days. This is a key consideration for buyers who should ensure they meet the co-op’s financial requirements.
When it comes to the Land Transfer Tax, the process is different for co-op purchases compared to condominiums. Since no title deed is transferred, the Revenue Ministry requires buyers to pay a Land Transfer Tax on the value of the shares being purchased.
Co-ownership is a hybrid model that blends characteristics of both co-ops and condominiums. In a co-ownership, the buyer purchases a percentage interest in a property, typically a freehold interest. This percentage is recorded on the title, which means the buyer technically owns part of the entire building, rather than shares in a corporation.
Much like co-op owners, co-ownership buyers acquire an exclusive right to occupy a specific unit, which is outlined in an occupancy agreement. Before leasing the unit, it’s recommended that co-owners consult with a solicitor to ensure they can regain possession if they need the unit for personal use or future sale.
Co-ownerships are typically managed by a Board of Directors, and the day-to-day operations are handled by a management company. Similar to condominiums, buyers may not need Board approval for a purchase, though some co-ownerships may require approval as outlined in the co-ownership agreement.
When it comes to Land Transfer Tax, co-ownerships are treated like freehold properties, meaning the buyer will pay the Land Transfer Tax on the sale price of the unit, similar to a traditional home purchase.
Regardless of the type of housing tenure, there are some key factors to consider before making a purchase:
Board Approval: For both co-ops and co-ownerships, buyers should understand the approval process and criteria used by the Board. Ensure there are no unreasonable restrictions on resale that could impact future marketability.
Estoppel Certificates: These documents are essential for understanding the financial health of the property. They provide insight into common area maintenance fees, upcoming assessments, and any litigation that may affect the property. Buyers should always request an Estoppel Certificate before purchasing.
Financial Health: Review the building’s financial statements and budget. If you’re considering a co-op or co-ownership, check if there’s a reserve fund in place for major repairs and replacements, particularly in older buildings.
Financing Challenges: Co-ops and co-ownerships often involve more complex financing arrangements. Buyers may need to provide larger down payments and secure loans with lower limits. This is less of an issue with condominiums, where financing is more accessible.
While purchasing a co-op or co-ownership unit can be more complex than buying a condominium, it offers an opportunity to enter the housing market at a potentially lower price point—sometimes as much as 40% less than a similar condo in the same area. As long as the property is well-managed, documented, and structured similarly to a condominium, it can be a sound investment.
With the right guidance, navigating co-op and co-ownership transactions can be straightforward. If you’re considering any of these housing options, it’s essential to work with an experienced real estate agent who understands the nuances of each type of ownership. With the right approach, these properties can offer excellent value and long-term potential.
I’m very excited to be partnering with Bosley Real Estate to provide you with the exceptional, professional representation you need to protect and promote your best interests. Bosley Real Estate....
A second set of rental rules in Ontario are set to take effect Sept. 21. Here is a link to Ontario Tribunals Page with information on the changes. The same information is presented here by the
Canada’s federal ban on foreign homebuyers is scheduled to expire January 1, 2027. With the deadline approaching, the government has yet to confirm whether it plans to extend the restrictions
According to recnt numbers from the Toronto Regional Real Estate Board (TRREB), Toronto home prices continued to soften in July, but the bigger story may not be the decline in prices. It may be what
For the first time in five years, average home prices in the Greater Toronto Area have slipped below the $1 million mark — a meaningful psychological and financial milestone that signals a
Should you require assistance in navigating our website or searching for real estate, please contact our offices at 416-322-8000.
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Bosley Real Estate Ltd. may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 2:47 PM UTC
Show More...